If you’re an American living in Japan, you already deal with Japanese taxes — income tax, resident tax, possibly consumption tax. But here’s what catches many people off guard: you may still need to file a US tax return each year, no matter how long you’ve lived in Japan.
The United States taxes based on citizenship, not residence. If you hold a US passport or a green card, the IRS expects to hear from you — even if every yen you earn comes from a Japanese employer and you haven’t set foot in the US for years. Green card holders are generally treated as US tax residents unless that status has been properly terminated for US tax purposes.
The good news: filing doesn’t necessarily mean paying. Between the Foreign Earned Income Exclusion and the Foreign Tax Credit, many Americans in Japan owe little or nothing to the IRS. The US-Japan Tax Treaty may matter in specific cases, but treaty benefits are limited for US citizens and green card holders because the United States often preserves the right to tax them as US persons. And the penalties for not filing can be severe.
This article is general information for US taxpayers living in Japan and is not tax, legal, or accounting advice. US international tax rules are fact-specific; consult a qualified tax professional for your situation.
Who Must File?
In this article, “Americans” means US citizens and green card holders for US tax purposes.
US citizens and green card holders living in Japan are subject to US tax filing rules. You generally must file a US federal tax return if your worldwide income exceeds the filing threshold for your status, or if another filing trigger applies. These rules generally apply to:
- US citizens living in Japan, regardless of how long you’ve been here
- US green card holders living in Japan, unless you have formally terminated your resident status for US tax purposes
The filing threshold for 2025 (filed in 2026) is $15,750 for single filers under 65 and $31,500 for married filing jointly when both spouses are under 65. These thresholds are based on worldwide gross income — not just US-source income — and foreign earned income is counted when determining whether you must file.
Self-employed taxpayers generally must file if net earnings from self-employment are $400 or more, even if gross income is below the standard filing threshold.
Even if you’re below the threshold, you should still file if you want to claim the Foreign Earned Income Exclusion or Foreign Tax Credit.
Source: IRS — Check If You Need to File a Tax Return | IRS — Publication 54
Key Deadlines
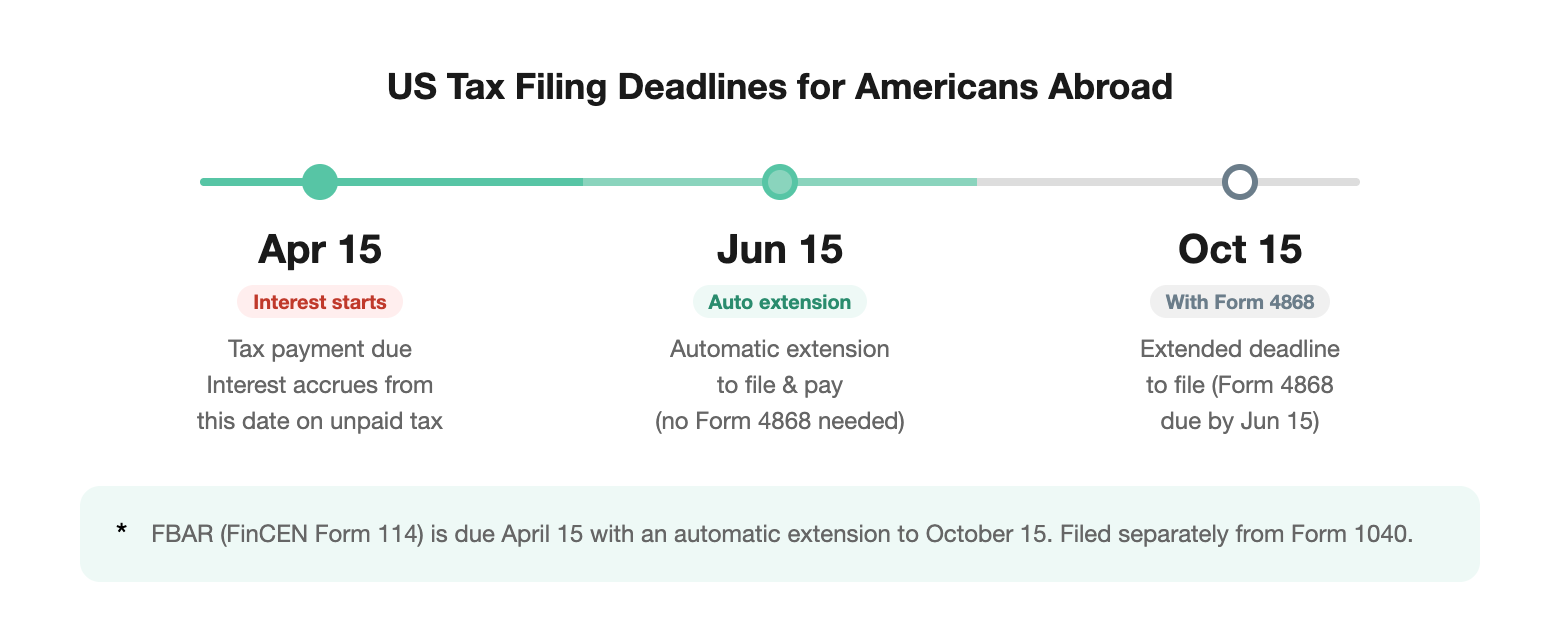
| Deadline | What |
|---|---|
| April 15 | Regular US tax deadline and interest start date for unpaid tax |
| June 15 | Automatic 2-month extension to file and pay for qualifying taxpayers abroad — no Form 4868 needed for this extension, but interest still runs from April 15 on unpaid tax |
| April 15 (of the following year) | FBAR deadline (FinCEN Form 114) with automatic extension to October 15 |
| October 15 | Additional filing extension for qualifying taxpayers abroad, if Form 4868 is filed by June 15 |
Source: IRS — Publication 54, Tax Guide for US Citizens and Resident Aliens Abroad
What Forms Do You Need?
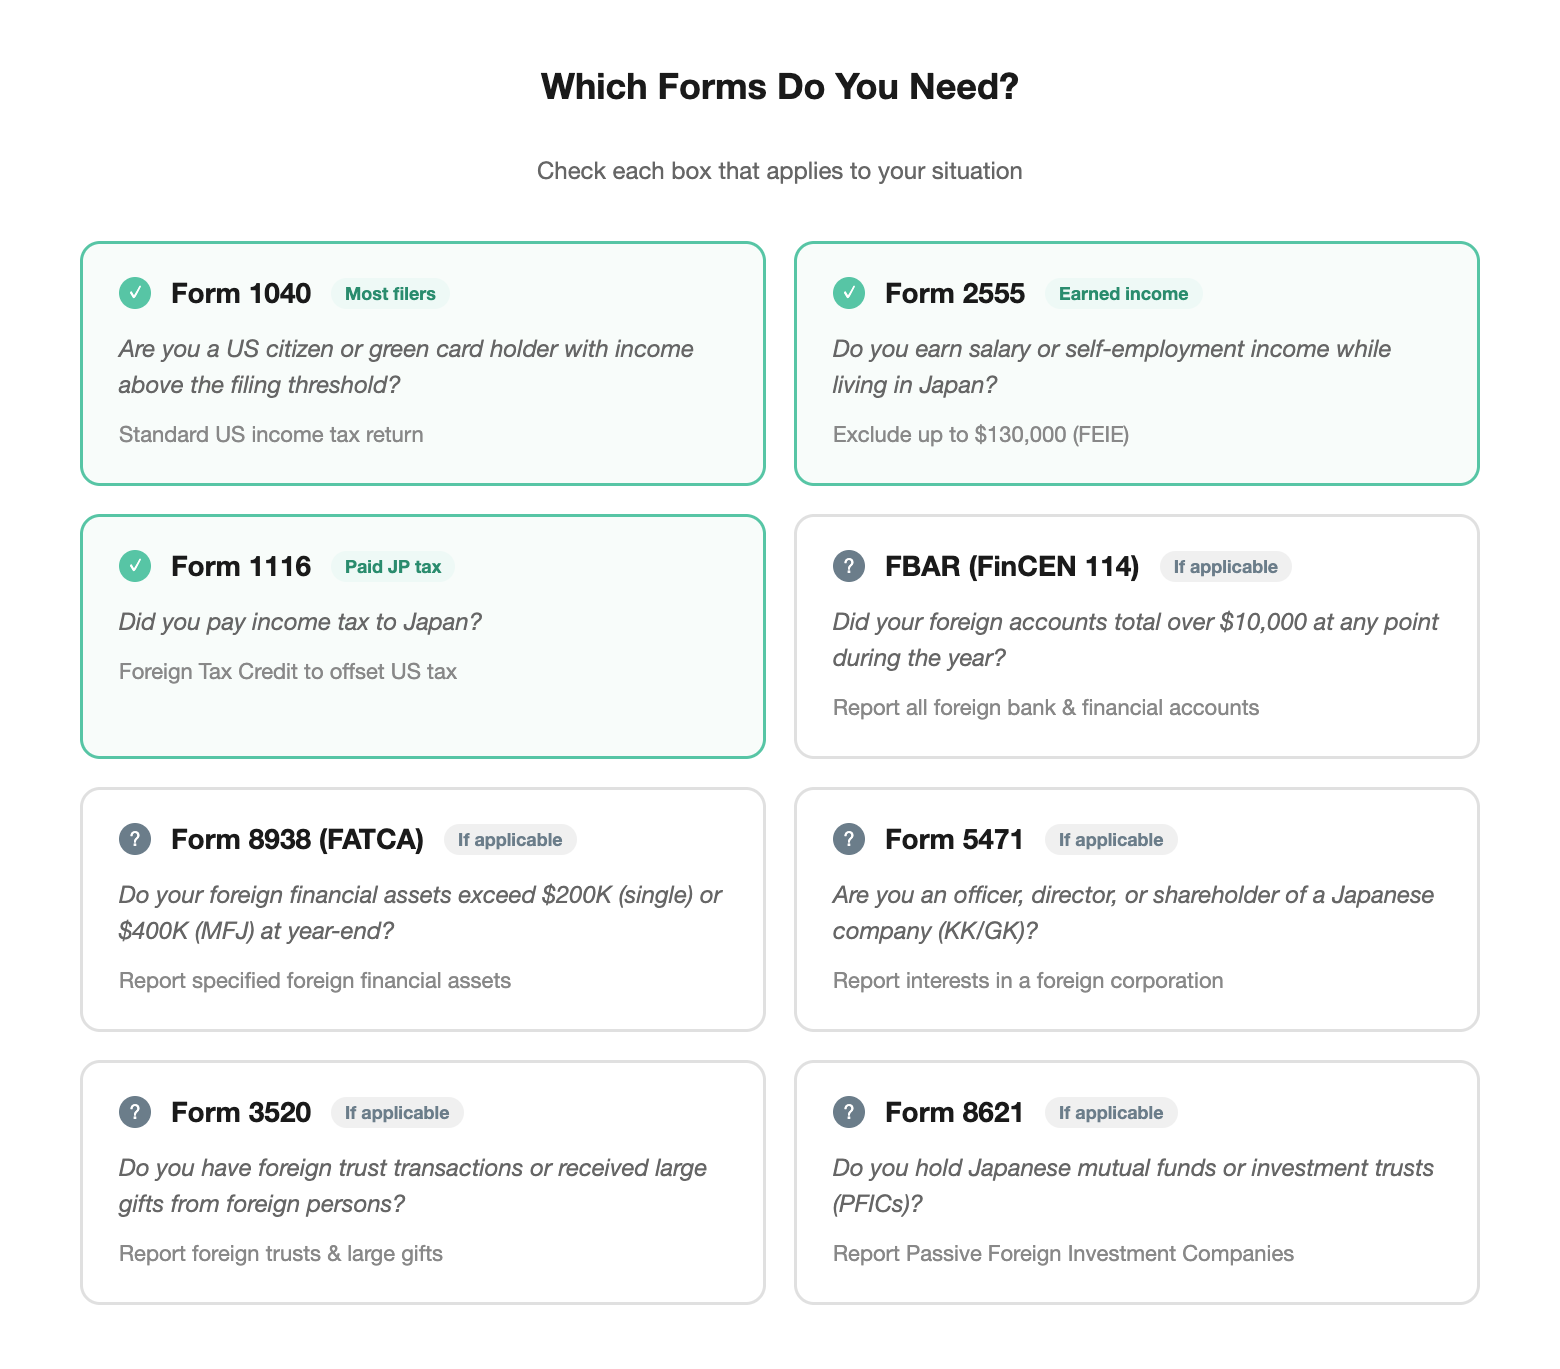
Here’s where it gets complicated. Depending on your situation, you may need to file several forms beyond the standard Form 1040:
| Form | Who Needs It | Purpose |
|---|---|---|
| Form 1040 | Taxpayers who meet a filing requirement or need to claim an exclusion, credit, or election | Standard US income tax return |
| Form 2555 | Qualifying taxpayers with foreign earned income (salary or self-employment) | Claim the Foreign Earned Income Exclusion (up to $130,000 for 2025) |
| Form 1116 | Taxpayers claiming a Foreign Tax Credit for eligible Japanese income taxes, unless an exception applies | Claim the Foreign Tax Credit to offset US tax |
| FinCEN Form 114 (FBAR) | Aggregate foreign accounts over $10,000 at any point during the year | Report foreign bank and financial accounts |
| Form 8938 (FATCA) | Single/MFS living abroad: over $200,000 at year-end or $300,000 at any time. MFJ living abroad: over $400,000 at year-end or $600,000 at any time | Report specified foreign financial assets |
| Form 5471 | Certain officers, directors, or shareholders of a foreign corporation, including some KK/GK structures | Report interests in a foreign corporation |
| Form 3520 | Certain foreign trust transactions, distributions, or large gifts/bequests from foreign persons | Report foreign trusts and large foreign gifts |
| Form 8621 | US persons who directly or indirectly own PFICs, which can include some non-US mutual funds or investment trusts | Report Passive Foreign Investment Companies (PFICs) |
We’ll cover each of these in detail in separate articles. For now, the key point: the reporting requirements go far beyond Form 1040. Penalties vary by form and facts, but some missed international information returns can trigger penalties of $10,000 or more.
Note: FBAR and Form 8938 are separate reporting regimes. Some accounts or assets may appear on both, while some assets may be reportable on one but not the other.
Source: IRS — Form 1116 Instructions | IRS — FATCA/Form 8938 Summary | IRS — Instructions for Form 3520 | IRS — About Form 5471 | IRS — Form 8621 Instructions
How to Avoid Paying US Tax Twice
Japan’s income tax burden is often higher than the US tax on the same income, depending on income level and facts. This works in your favor: you have two main tools to eliminate or reduce your US tax bill.
Foreign Earned Income Exclusion (FEIE) — If your tax home is abroad and you meet either the bona fide residence test or the physical presence test (330 full days outside the US in a 12-month period), you may be able to exclude up to $130,000 of qualifying foreign earned income for tax year 2025. Note: the FEIE reduces income tax but does not by itself eliminate US self-employment tax.
Foreign Tax Credit (FTC) — Eligible Japanese income taxes may generate a Foreign Tax Credit that reduces your US tax, subject to IRS limits and income-category rules. Because Japanese tax rates are often higher, many Americans in Japan owe little or no US income tax after the credit — but the result depends on the facts.
You can use one or both, but the strategy depends on your income level and type. We cover the details in our FEIE and Foreign Tax Credit guides.
Source: IRS — Foreign Earned Income Exclusion | IRS — Foreign Tax Credit | IRS — Self-Employment Tax for Businesses Abroad | SSA — Totalization Agreement with Japan
What Happens If You Haven’t Been Filing?
If you’ve been living in Japan for years and never filed a US return, you’re not alone — and there may be a way to get current without penalties.
The IRS offers the Streamlined Filing Compliance Procedures, designed specifically for expats who weren’t aware of their filing obligations. If you qualify for the Streamlined Foreign Offshore Procedures and certify that your failure to file was non-willful, you generally:
- File the last 3 years of tax returns
- File the last 6 years of FBARs
- May avoid penalties entirely
This is a legitimate IRS program, not a loophole. We cover the full process in our Streamlined Filing guide.
Source: IRS — Streamlined Filing Compliance Procedures | IRS — FBAR Overview
Frequently Asked Questions
Do Americans in Japan have to file US taxes?
Yes. US citizens and green card holders generally must file a federal tax return if their worldwide income exceeds the filing threshold, regardless of where they live. Some people may need to file even below that threshold — for example, self-employed taxpayers or those claiming certain exclusions, credits, or elections.
Do I owe US tax if I already pay Japanese tax?
Usually not, or very little. The Foreign Tax Credit lets you reduce your US tax by eligible Japanese income taxes you’ve paid, subject to IRS limits. Because Japanese rates are often higher, many Americans in Japan owe little or no US income tax — but you still must file.
Do I need to report my Japanese bank accounts?
Yes, if your total balances in all foreign accounts exceeded $10,000 at any point during the year. You must file an FBAR (FinCEN Form 114) electronically by April 15, with an automatic extension to October 15.
What if I haven’t filed for several years?
The IRS Streamlined Filing Compliance Procedures may allow you to catch up by filing the last 3 years of tax returns and 6 years of FBARs, potentially without penalties. You must certify that the failure was non-willful.
Next Steps
This article is part of our series on US tax obligations for Americans in Japan. Dive deeper into the topics that apply to you:
- Foreign Tax Credit — How to claim credit for Japanese taxes paid
- Foreign Earned Income Exclusion — Exclude up to $130,000 of earned income
- FBAR Filing — Reporting your Japanese bank accounts
- Form 5471 — If you own a Japanese company (KK or GK)
- PFICs and Form 8621 — Why Japanese investment funds can create complex US tax reporting
- Streamlined Filing — How to catch up without penalties